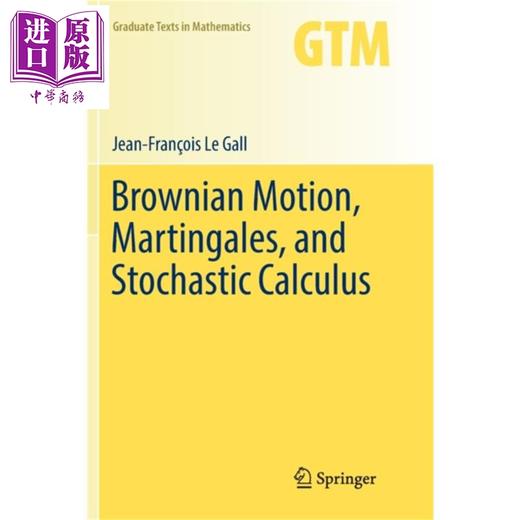
【中商原版】布朗运动鞅和微积分 Brownian Motion Martingales and Stochastic 英文原版 Jean Francois Le Gall
| 运费: | ¥ 0.00-16.00 |
| 库存: | 1 件 |
商品详情
布朗运动,鞅和随机微积分 Brownian Motion, Martingales, and Stochastic Calculus
基本信息
Series:Graduate Texts in Mathematics
Format:Paperback / softback 273 pages, Illustrations; Bibliography; Tables, color; Illustrations, color; 4 Illustrations, black
Publisher:Birkhauser Verlag AG
Imprint:Birkhauser Verlag AG
Edition:Softcover Reprint of the Original 1st 2016 ed.
ISBN:9783319809618
Published:27 May 2018
Weight:408g
Dimensions:234 x 156 x 15 (mm)
页面参数仅供参考,具体以实物为准
书籍简介
本书在连续半鞅的一般框架内对随机积分和随机微积分进行了严格的、自足的介绍。书中详细介绍了随机微积分的主要工具,包括Itô公式、可选的停止定理和Girsanov定理,以及许多说明性例子。本书还包括马尔科夫过程的介绍,以及对随机微分方程解的应用和布朗运动与偏微分方程之间的联系。在j结局章中讨论了半鞅的局部时间理论。
自伊藤发明以来,随机微积分已被证明是现代概率论中重要的技术之一,并被用于新的理论进展以及数学金融等其他领域的应用中。布朗运动、马廷格和随机微积分为对这种发展感兴趣的读者提供了强大的理论背景。
初学的研究生或高年级的本科生将受益于这种对概率论的一个重要领域的详细方法。本书的重点是简明有效的表述,而没有对数学的严谨性作出任何让步。作者在法国富盛名的两所大学的研究生课程中教授这些材料已有数年。本书提供了证明的全部细节,因此特别适合于自学。大量的练习帮助读者熟悉随机微积分的工具。
This book offers a rigorous and self-contained presentation of stochastic integration and stochastic calculus within the general framework of continuous semimartingales. The main tools of stochastic calculus, including Itô’s formula, the optional stopping theorem and Girsanov’s theorem, are treated in detail alongside many illustrative examples. The book also contains an introduction to Markov processes, with applications to solutions of stochastic differential equations and to connections between Brownian motion and partial differential equations. The theory of local times of semimartingales is discussed in the last chapter.
Since its invention by Itô, stochastic calculus has proven to be one of the most important techniques of modern probability theory, and has been used in the most recent theoretical advances as well as in applications to other fields such as mathematical finance. Brownian Motion, Martingales, and Stochastic Calculus provides a strong theoretical background to the reader interested in such developments.
Beginning graduate or advanced undergraduate students will benefit from this detailed approach to an essential area of probability theory. The emphasis is on concise and efficient presentation, without any concession to mathematical rigor. The material has been taught by the author for several years in graduate courses at two of the most prestigious French universities. The fact that proofs are given with full details makes the book particularly suitable for self-study. The numerous exercises help the reader to get acquainted with the tools of stochastic calculus.
作者简介
Jean-François Le Gall是一位知名的概率论和随机过程专家。他的主要研究成就涉及布朗运动、超级过程及其与偏微分方程的联系,以及近来随机树和随机图。他曾获多个国际数学奖,包括Loeve奖和Fermat奖,并在2014年国际数学家大会上作了全体演讲。他目前是巴黎南方大学的数学教授和法国科学院院士。
Jean-François Le Gall is a well-known specialist of probability theory and stochastic processes. His main research achievements are concerned with Brownian motion, superprocesses and their connections with partial differential equations, and more recently random trees and random graphs. He has been awarded several international prizes in mathematics, including the Loeve Prize and the Fermat Prize, and gave a plenary lecture at the 2014 International Congress of Mathematicians. He is currently a professor of mathematics at Université Paris-Sud and a member of the French Academy of Sciences.
- 中商进口商城 (微信公众号认证)
- 中商进口商城中华商务贸易有限公司所运营的英美日韩港台原版图书销售平台,旨在向内地读者介绍、普及、引进最新最有价值的国外和港台图书和资讯。
- 扫描二维码,访问我们的微信店铺
- 随时随地的购物、客服咨询、查询订单和物流...