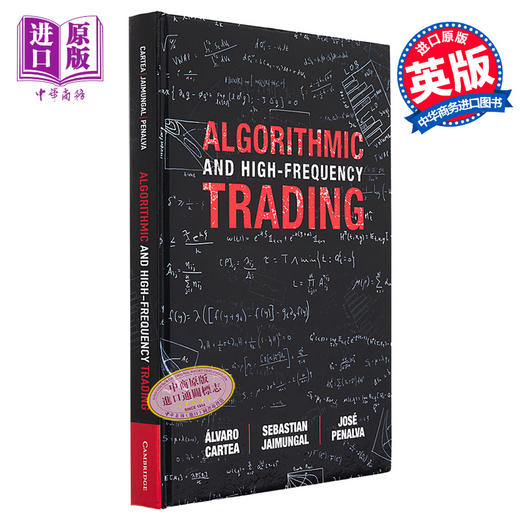
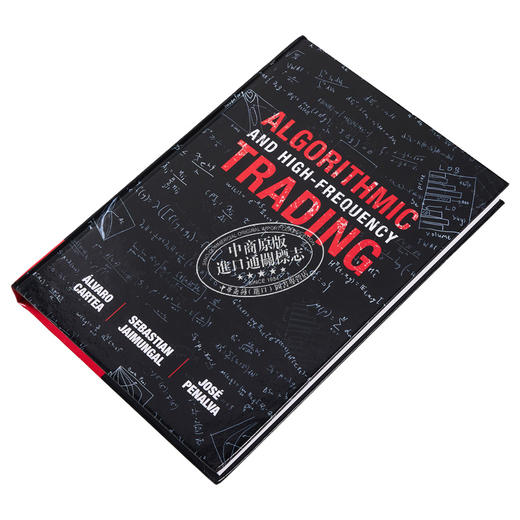
预售 【中商原版】算法和高频交易 Algorithmic and High Frequency Trading 英文原版 Alvaro Cartea 投资金融经济
| 运费: | ¥ 0.00-16.00 |
| 库存: | 1 件 |
商品详情
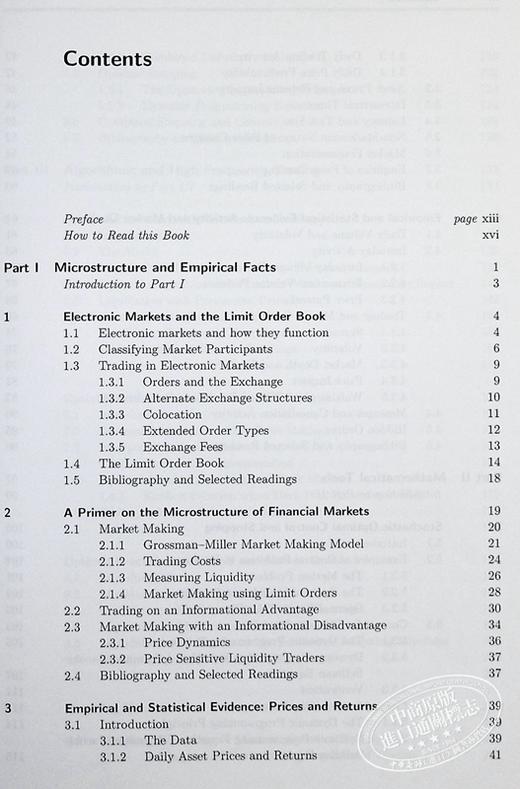
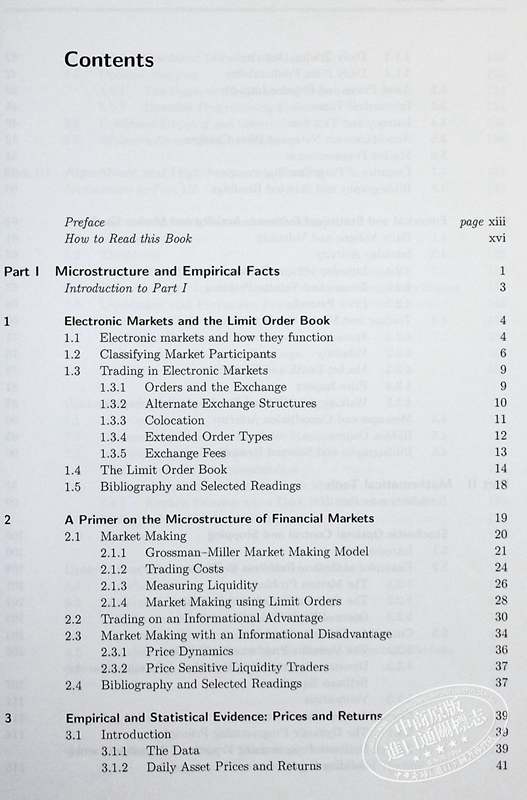
算法和高频交易 Algorithmic and High-Frequency Trading
基本信息
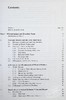
Format:Hardback 356 pages, 35 Tables, black and white; 42 Halftones, color; 5 Line drawings, unspecified; 33 Line dr
Publisher:Cambridge University Press
Imprint:Cambridge University Press
ISBN:9781107091146
Published:6 Aug 2015
Weight:786g
Dimensions:256 x 182 x 22 (mm)
信息仅供参考,具体以实物为准
书籍简介
交易算法的设计需要有可靠数据支持的复杂数学模型。在这本教科书中,作者为算法交易建立了各种模型,如执行大额订单、做市商、瞄准 VWAP 和其他时间表、交易资产对或资产集合,以及在暗池中执行。这些模型以交易所的运作方式、算法是否与更知情的交易者进行交易(逆向选择)以及超高频和低频市场参与者可获得的信息类型为基础。《算法与高频交易》是一本将复杂的数学建模、经验事实和金融经济学结合在一起的书籍,带领读者从基本概念到前沿研究和实践。如果您需要了解现代电子市场是如何运作的,哪些信息能提供交易优势,以及其他市场参与者会如何影响算法的盈利能力,那么本书就是您的选择。
The design of trading algorithms requires sophisticated mathematical models backed up by reliable data. In this textbook, the authors develop models for algorithmic trading in contexts such as executing large orders, market making, targeting VWAP and other schedules, trading pairs or collection of assets, and executing in dark pools. These models are grounded on how the exchanges work, whether the algorithm is trading with better informed traders (adverse selection), and the type of information available to market participants at both ultra-high and low frequency. Algorithmic and High-Frequency Trading is the first book that combines sophisticated mathematical modelling, empirical facts and financial economics, taking the reader from basic ideas to cutting-edge research and practice. If you need to understand how modern electronic markets operate, what information provides a trading edge, and how other market participants may affect the profitability of the algorithms, then this is the book for you.
书籍评价
“[本书]是一本重要而及时的算法交易教科书。金融市场中的人类交易员已濒临灭绝,逐渐被计算机和算法所取代。在这个新世界里,设计和编码交易策略需要了解市场微观结构、金融市场价格形成的基本经济原理,以及价格动态和交易活动的风格化事实。它还需要特定的数学工具,如随机控制,并了解如何使用这些工具来解决交易问题。《算法与高频交易》的特别之处在于,它对这些主题进行了统一处理。我很喜欢阅读这本书,并强烈推给对算法交易中使用的数学模型感兴趣的学生或从业人员。”——Thierry Foucault,巴黎高等商学院
“本书是一本从动态随机优化的现代视角出发,基于前沿研究成果,全面介绍算法交易和高频交易中的策略的著作。其他书籍涵盖了高频市场动态的机制和统计,但没有一本能如此深入地涵盖数学方面。这将是一本很好的优化交易研究生课程教科书。”——罗伯特-阿尔姆格伦,《量化经纪人
“这本教科书是对算法交易和高频市场文献的有益补充。它将前沿的数学模型应用于实际算法的分析和实施,填补了这一重大空白。作者运用微观结构理论、金融数据分析和数学模型的独特结合,带领读者穿越高频市场的迷宫,详细介绍了交易所的运作方式以及交易所产生的数据种类。作者用通俗易懂的散文描述了交易算法及其实际应用,并用富有启发性的模拟进行了说明。该书是金融数学和工程专业研究生和研究人员以及该领域从业人员的理想读物。”——普林斯顿大学 René Carmona
作者简介
阿尔瓦罗-卡尔特亚是伦敦大学学院金融数学系教授。在加入伦敦大学学院之前,他是马德里卡洛斯三世大学(Universidad Carlos III, Madrid)的金融学副教授(2009-2012 年),2002 年至 2009 年,他是伦敦大学伯克贝克经济、数学和统计学院的讲师(终身职)。他曾任牛津大学埃克塞特学院摩根大通金融数学讲师。
Sebastian Jaimungal 是多伦多大学统计科学系副教授兼研究生系主任,教授数学金融博士和硕士课程。他为大型银行和对冲基金提供咨询,专注于实施先进的衍生品估值引擎和算法交易策略。他还是《SIAM 金融数学期刊》、《国际理论与应用金融期刊》、《风险》期刊和 Argo 时事通讯的副编辑。Jaimungal 是 SIAM 金融工程与数学活动小组的副主席,他的研究成果广泛发表在学术和从业期刊上。他的研究兴趣包括高频和算法交易、应用随机控制、均场博弈、实物期权以及商品模型和衍生品定价。
何塞-佩纳尔瓦(José Penalva)是马德里卡洛斯三世大学(Universidad Carlos III de Madrid)的副教授,教授金融学博士和硕士课程以及本科课程。他目前正在研究信息模型和市场微观结构,其研究成果已发表在《计量经济学》和其他学术期刊上。
Álvaro Cartea is a Reader in Financial Mathematics at University College London. Before joining UCL, he was Associate Professor of Finance at Universidad Carlos III, Madrid (2009–2012) and from 2002 to 2009 he was a Lecturer (with tenure) in the School of Economics, Mathematics and Statistics at Birkbeck, University of London. He was previously JP Morgan Lecturer in Financial Mathematics at Exeter College, Oxford.
Sebastian Jaimungal is an Associate Professor and Chair of Graduate Studies in the Department of Statistical Sciences, University of Toronto, where he teaches in the PhD and Masters in Mathematical Finance programs. He consults for major banks and hedge funds focusing on implementing advance derivative valuation engines and algorithmic trading strategies. He is also an associate editor for the SIAM Journal on Financial Mathematics, the International Journal of Theoretical and Applied Finance, the journal Risks and the Argo newsletter. Jaimungal is Vice Chair for the SIAM activity group on Financial Engineering and Mathematics, and his research has been widely published in academic and practitioner journals. His recent interests include high-frequency and algorithmic trading, applied stochastic control, mean-field games, real options, and commodity models and derivative pricing.
José Penalva is an Associate Professor at the Universidad Carlos III de Madrid, where he teaches in the PhD and Masters in Finance programs, as well as at the undergraduate level. He is currently working on information models and market microstructure and his research has been published in Econometrica and other top academic journals.
- 中商进口商城 (微信公众号认证)
- 中商进口商城中华商务贸易有限公司所运营的英美日韩港台原版图书销售平台,旨在向内地读者介绍、普及、引进最新最有价值的国外和港台图书和资讯。
- 扫描二维码,访问我们的微信店铺
- 随时随地的购物、客服咨询、查询订单和物流...